1. Identify
Segment open invoices into current, 1–30, 31–60, 61–90 and 90-plus-day aging buckets.
Turn invoices into structured digital payment requests, give Payers visibility before they authorize payment, and connect real-time status data to accounts receivable aging and reconciliation.
Activate My Real-Time Payments Request for Payments (RfP™) — Start in About 3 MinutesThe three-minute step begins an online intake. Availability, underwriting, pricing, network reach and final approval depend on Today Payments, participating financial institutions and applicable program requirements.
An aging report tells a business which invoices are late. A Request for Payment can help the business act on that information. By linking invoice context, due dates, Payer responses and payment status, finance teams can move from passive A/R reporting toward a controlled collection workflow.
Today Payments, Inc. positions its accounting-fintech software as an orchestration layer between business systems and participating banks or credit unions. We are not a bank, the Federal Reserve or the FedNow Service. The FedNow Service is the Federal Reserve’s instant-payment infrastructure for participating depository institutions, which send and receive transactions on behalf of customers.

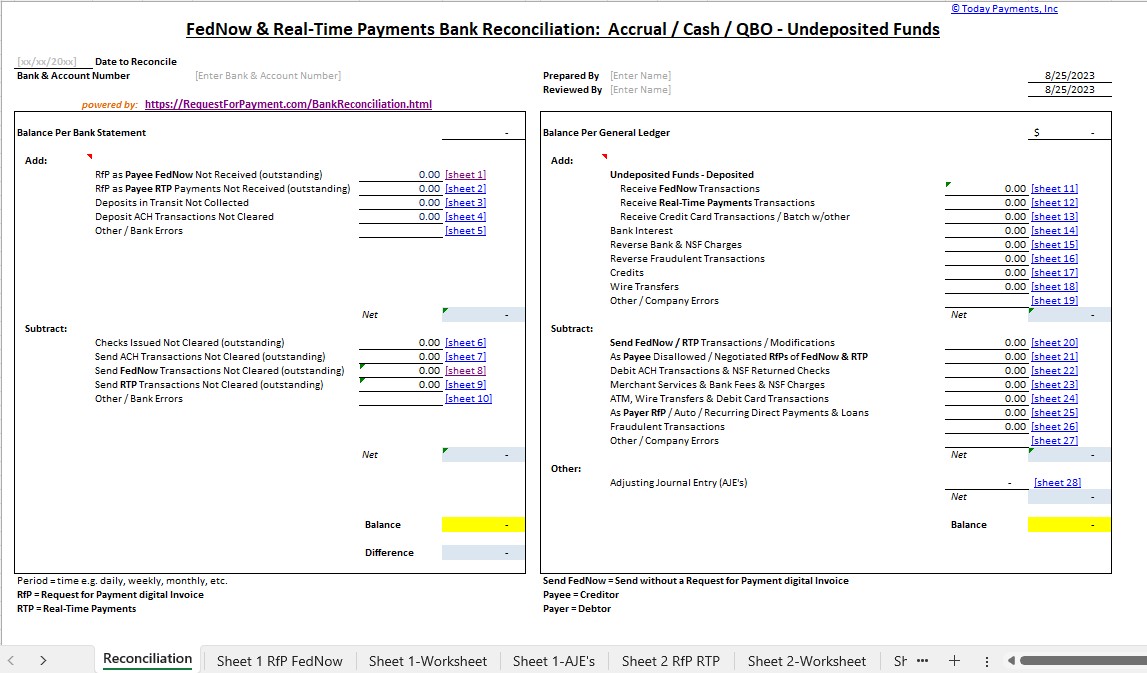
To support merchants and finance teams of all sizes, TodayPayments.com offers free downloadable templates, including:
Traditional check positive pay compares presented checks with a company-issued file. In a digital RfP workflow, “positive pay” is a business-control concept: the Payer receives a payment request and can review invoice details before instructing its financial institution to send an instant credit transfer. The RfP itself is a non-monetary message; it does not pull money from the Payer’s account.
This approve-before-pay design can support separation of duties, vendor verification, exception routing and an auditable decision trail. After authorization, the Payer’s participating financial institution may initiate the associated instant payment, subject to its controls and service terms.
Segment open invoices into current, 1–30, 31–60, 61–90 and 90-plus-day aging buckets.
Create a structured RfP tied to the customer, invoice, amount, currency, due date and remittance reference.
Deliver the request through an eligible bank channel or supported digital experience, with a secure hosted page when more invoice detail is needed.
Let the Payer review the request and follow its bank’s available response and payment options.
Monitor sent, delivered, responded, expired, paid and exception states without treating an RfP response as proof of settlement.
Match confirmed payment information to the invoice and update A/R aging, cash application and management reporting.
| Category | Representative parameters | Operational purpose |
|---|---|---|
| Request identity | Message ID, creation time, request ID, end-to-end ID | Uniqueness, traceability and duplicate control |
| Payee/creditor | Legal or display name, account or proxy/alias, servicing institution | Identifies who is requesting payment and where funds are intended to go |
| Payer/debtor | Name and routing identifiers permitted by the implementation | Directs the request to the intended Payer relationship |
| Payment terms | Requested amount, USD currency, requested execution date, expiry | States how much is requested and when action is expected |
| Invoice context | Invoice number, customer number, purchase order, service period, tax or discount references | Supports review, cash application and dispute handling |
| Remittance data | Structured references and/or permitted unstructured text | Connects the payment request and resulting payment to receivables |
| Presentation link | Secure HTTPS link or tokenized hosted-payment-page reference, where supported | Provides detailed invoice documents, line items and Payer options |
| Control data | Purpose, category, channel, risk signals, delivery and response status | Supports routing, alerts, audit and exception management |
A 140-character description and hyperlink can be useful product-design choices, but they are not universal FedNow requirements. Allowed fields, lengths, aliases and links depend on the applicable FedNow message specification, participating financial institutions and the end-user channel.
Send a clear digital request as soon as an invoice is ready and enable an eligible Payer to act without rekeying payment details.
Connect request status, Payer response and confirmed payment events to aging queues and collection priorities.
Present invoice context before payment authorization, supporting review, approval policies and exception handling.
Carry invoice and remittance references that improve automated matching and reduce unidentified cash.
Use internal merchant or location identifiers to report by division, subsidiary, franchise, brand or deposit relationship.
Support eligible use cases across online invoices, mobile, email, SMS, QR, POS, retail, wholesale and MOTO workflows.
A business cannot open an account directly with the FedNow Service. FedNow participation is available to eligible financial institutions, and customer access is delivered through participating banks, credit unions and their service providers. Today Payments can begin a merchant-services intake and help identify an eligible connection path.
Eligible entity types may include: sole proprietorships, Schedule C businesses, partnerships, LLCs, S corporations, C corporations, nonprofits and other organizations. Acceptance is not automatic; approval and supported industries depend on underwriting, participating financial institutions and applicable rules.
A standing approval can let a Payer pre-authorize future payments that meet agreed conditions, such as a named biller, maximum amount, frequency and expiration date. The Payer’s financial institution or payment provider must support the arrangement, and the merchant must retain clear authorization records and follow applicable consumer-protection, error-resolution, cancellation and notice requirements.
Recurring FedNow-enabled payments are credit transfers initiated through the Payer’s provider; an RfP is not a debit transaction and cannot independently withdraw funds. Once an instant payment is accepted and settled, funds generally become available quickly and the payment is designed to be final, but legitimate return requests and fraud/error procedures may still apply. Therefore, “no card chargebacks” should never be marketed as “no returns under any circumstances.”
FedNow uses ISO 20022 messages, but the Federal Reserve’s current implementation guide—not the unrestricted global ISO schema—controls what is mandatory, optional, conditional and permitted for a FedNow RfP. A production implementation should validate against the exact current FedNow specification available through MyStandards.
| Data group | Practical minimum |
|---|---|
| Business Application Header | Sender, receiver, business message identifier, message definition identifier, service identifier and creation date/time as required by the implementation. |
| Group header | Unique message identification, creation timestamp, transaction count where required, and initiating-party information. |
| Payment information | Payment-information ID, payment method/context, requested execution date or timing data, and creditor/payment routing information. |
| Transaction identity | Instruction ID and/or end-to-end ID plus a unique RfP or transaction reference. |
| Amount | Requested amount and supported currency, ordinarily USD for domestic FedNow transactions. |
| Parties and agents | Creditor/Payee and debtor/Payer data, along with their financial institutions or routing identifiers, as required or available. |
| Account or proxy | Creditor and debtor account identifiers or supported proxy/alias information according to the participating institutions’ implementation. |
| Remittance | Sufficient structured or permitted unstructured reference data to associate the request and resulting payment with the invoice or obligation. |
| Expiry and controls | Request expiry, purpose, requested response and other conditional elements when required by the use case or implementation. |
ISO’s current catalogue identifies pain.013 as the Creditor Payment Activation Request and pain.014 as its status report. Version numbers evolve. Do not hard-code a generic version or assume every globally available element is accepted by FedNow.
A business can send structured invoice information in a FedNow RfP workflow so the Payer can review the Payee, amount, due date and remittance details before authorizing a credit transfer through a participating financial institution. This creates an approve-before-pay control that can complement accounts-payable policies and vendor verification.
Connecting RfP status and confirmed payment data to A/R aging can help collectors prioritize unpaid invoices, identify expired or unanswered requests, and match incoming funds to customer and invoice references. The result is a more current collection queue and less manual cash application.
Merchants can begin an online intake with Today Payments through Real-TimePayments.com. Today Payments can collect business requirements and help coordinate an eligible service path, while the participating bank, credit union and applicable providers determine availability and final approval.
Today Payments can organize internal merchant identifiers, locations and accounting mappings across multiple business units and eligible financial-institution relationships. Whether a phone number, email address or other proxy can be used depends on the relevant directory, bank and service configuration.
Your A/R team should not have to choose between invoice detail, Payer control and payment speed. Today Payments brings these functions together through structured Request for Payment workflows, hosted payment experiences, multi-entity reporting and accounting integration.
Start online in about three minutes. Tell us how your business bills customers, which entities and accounts you manage, and how you want payment data reconciled. We’ll help map an eligible route from invoice to request, authorization, payment confirmation and cash application.
Activate My Real-Time Payments RfP™